Health Insurance: Reasons Your Choices Could Shrink This Autumn
Health insurance choices can shift over time. Discover the reasons behind premium increases, why some insurers might leave certain markets, and tips on getting ready for Open Enrollment.
Warning: Your health insurance choices may shrink this fall
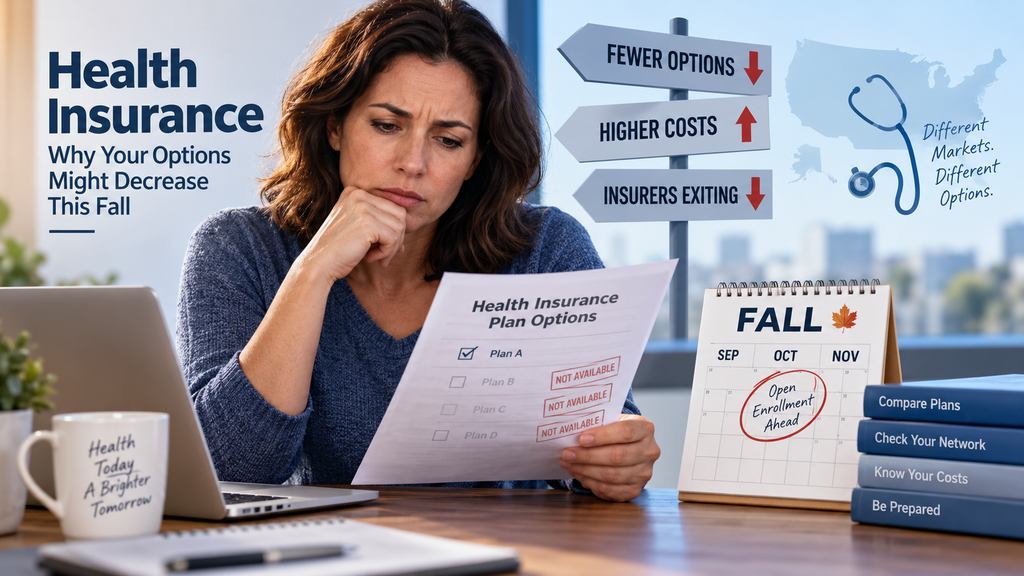
For some Americans, the availability of health insurance plans could become more restricted this coming fall.
Some insurers are proposing premium hikes, while a few carriers plan to withdraw from certain ACA Marketplace regions.
Meanwhile, seven insurers have revealed intentions to leave select Marketplace areas, while five others have announced moves into new regions.
This doesn’t mean everyone will face fewer options. Instead, your local health insurance offerings may look quite different this fall.
Why Are Health Insurance Choices Becoming More Limited?
Health insurance selections may reduce as some insurers pull out of ACA Marketplace regions while others adjust the locations where they provide coverage.
This shift results from a mix of rising healthcare expenses, evolving enrollment trends, and the end of enhanced ACA premium assistance.
According to KFF, the average count of insurers offering plans in each state dropped from 9.6 in 2025 to 9.0 in 2026.
This is important because the variety of insurers in your area directly impacts how many plans you can review and choose from.
Are Health Insurers Withdrawing from the ACA Marketplace?
Yes. Several insurers have revealed plans to pull out of certain ACA Marketplace regions ahead of 2027.
A clear example is Cigna, which has declared it will leave the individual market in all 11 states where it currently operates.
That said, the overall marketplace isn’t contracting everywhere.
In fact, some insurers are expanding into new states, so consumers in some regions might see more plan choices instead of fewer.
Keep in mind: nationwide patterns won’t always reflect changes in your local area.
Will Health Insurance Prices Rise?
It’s possible. Insurers are suggesting a median 15% hike in premiums on the ACA Marketplace.
KFF reviewed rate submissions from 276 insurers in all 50 states plus D.C., revealing a 15% median proposed rise.
This doesn’t guarantee your premium will go up by exactly 15%, though.
The final cost you pay depends on factors such as:
- Age;
- ZIP code;
- Household income;
- Household size;
- Plan type;
- Metal tier;
- Eligibility for premium tax credits;
- Available insurers.
So keep in mind that national averages may not reflect your own rate change.
What’s Driving the Rise in ACA Health Insurance Premiums?
Multiple reasons are pushing premiums higher, including rising healthcare expenses and shifts in the ACA Marketplace’s risk pool.
A key reason is the end of the enhanced premium tax credits that were offered through the close of 2025.
For many families, this represents a significant adjustment to their monthly expenses.
What Happened to ACA Premium Tax Credits?
The enhanced ACA premium tax credits ended at the conclusion of 2025, causing many Marketplace buyers to face higher coverage costs.
Introduced in 2021, these enhanced subsidies provided more financial aid to those using the Marketplace.
After they ended, many individuals faced increases in their net premium costs.
This change particularly affects those who lack employer-sponsored health coverage.
Are More Consumers Opting for Bronze Health Insurance Plans?
Indeed. According to KFF, the portion of Marketplace enrollees choosing Bronze plans rose from 30% in 2025 to 40% in 2026.
Meanwhile, enrollment in Silver plans dropped significantly, from 57% down to 43%.
Why is this important?
Because Bronze plans typically feature lower monthly premiums but come with higher deductibles and out-of-pocket expenses.
This makes them appealing for individuals who rarely need medical care.
However, those with frequent healthcare needs might face significantly higher costs when they seek treatment.
What If Your Doctor Isn’t Included in the New Plan’s Network?
Before changing health plans, make sure to verify your provider network. Many people overlook this step during Open Enrollment.
Confirm that your new plan includes coverage for:
- Primary care doctor
- Specialists
- Preferred hospital
- Urgent care
- Mental health providers
- Pharmacies
- Prescription medications
This step is crucial if you’re currently undergoing any medical treatments.
Saving on premiums won’t help if your favorite doctor isn’t included in your new plan’s network.
How to Prepare This September
Although Open Enrollment hasn’t begun, September is an ideal month to start getting ready.
Gathering all necessary details now will make the enrollment process smoother later on.
1. Evaluate Your Current Health Coverage
Review your existing plan details:
- Monthly premium
- Deductible
- Out-of-pocket maximum
- Doctors
- Hospitals
- Prescriptions
- Annual healthcare spending
Don’t depend on your memory alone.
Refer to your actual healthcare costs from the previous year.
2. Calculate Your Household Income for 2027
The income you expect to earn this year can impact your eligibility for financial help on the Marketplace.
HealthCare.gov considers details like your household size and projected income to determine which plans and savings options you qualify for.
Significant changes to your income can also impact how much you pay for health insurance.
3. List Your Essential Healthcare Providers
Make a note of the doctors and hospitals you want to keep in your coverage network.
Once 2027 plans are released, check if your providers are included in their networks.
Taking this simple precaution can save you from costly errors.
4. Review and Compare Plans Once 2027 Options Are Released
Avoid simply renewing without review.
Look at your current coverage alongside the new plans offered in your area.
This gives you a clearer picture than just comparing premiums.
What Do Personal Finance Experts Say About Health Insurance?
Leading personal finance sources in the U.S. each tackle health insurance topics from their own unique perspectives.
NerdWallet puts strong emphasis on comparing Marketplace plans, insurers, premiums, consumer complaints, quality ratings, and options tailored to specific states.
Bankrate highlights affordability and explores the various ways consumers can secure private health insurance coverage.
Investopedia covers wider shifts impacting healthcare users, including updates on Medicare and insurance policy developments.
CNBC Select often explores healthcare by highlighting the financial impact of medical bills and unexpected health emergencies.
What Key Information Is Missing From Most Health Insurance Guides?
Much of the health insurance advice out there zeroes in on which provider is the best choice.
However, for those facing 2027 plan changes, a different question matters more:
This article fills that practical gap.
The best choice isn’t always the highest-ranked national plan. It’s the one that fits your health needs, budget, and local doctor network.
Why September Is the Month to Focus On
The biggest error is delaying your research until right before the enrollment deadline.
By September, you should have a clear understanding of your current healthcare spending and what coverage features matter most to you.
This way, once 2027 plans and rates are released, you’ll be ready to evaluate them quickly.
This is especially crucial this year since insurers are proposing notable premium hikes and some carriers are adjusting their Marketplace involvement.
Being prepared can expand your choices, even if the overall market offers fewer plans.
Author’s Opinion
Don’t wait until Open Enrollment to start considering your health insurance options.
These figures highlight why it’s important to start paying attention now: insurers for 2027 are suggesting a median premium hike of 15%, while some are exiting certain Marketplace areas.
However, the story isn’t that “health insurance is vanishing.”
That’s an oversimplification. The key point is your local health insurance options might shift, so being prepared to shop around is essential.
If you’re self-employed, in between jobs, nearing retirement, or buying your own plan, don’t focus only on the monthly premium.
A plan that’s $50 cheaper each month might actually cost more overall if it has a much higher deductible or doesn’t include your preferred doctor.
When fall arrives, avoid renewing your health insurance without review. Evaluate your choices, network coverage, and costs carefully.
Recommended Content
Fed’s September meeting
Learn what savers should know about APYs, HYSAs, CDs and the Fed’s rate decision.
Continue reading * You will remain on the current website