When is the best moment to invest? Understanding the cost of waiting
Wondering if there’s an ideal moment to start investing? Discover why holding out for the perfect market timing might actually cost you, and how committing to long-term investing can be a smarter approach.
Why waiting for the perfect moment to invest is a common mistake
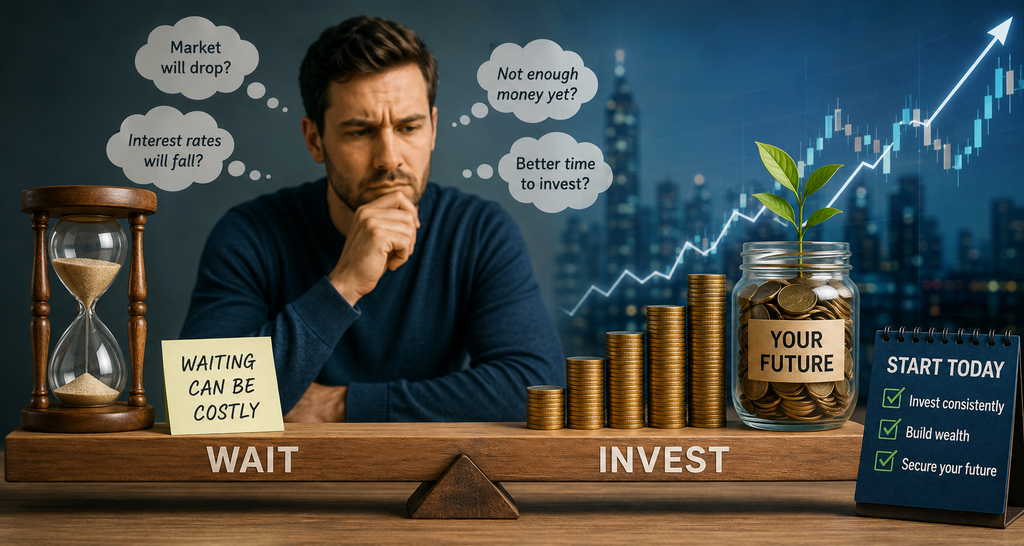
If you keep telling yourself you’ll only begin investing when the market dips, interest rates drop, or certain conditions align, you could be making the process more complicated than necessary.
The reality is there’s hardly ever an ideal time to invest. Markets tend to shift before most investors feel ready.
For anyone aiming to build a retirement fund, increase long-term savings, or just begin investing, a better question might be, “Is now the right moment to start investing?”
Is there truly a perfect time to invest?
In short, there is no consistently reliable “ideal” moment to begin investing.
Pinpointing the exact market bottom means knowing precisely when prices will stop dropping and when the rebound will start.
That’s the core challenge with timing the market: you must correctly decide both when to exit and when to re-enter.
This doesn’t mean you should recklessly invest funds you’ll need in the near future.
Rather, long-term investors should separate creating a thoughtful plan from endlessly waiting for flawless market timing.
Why Putting Off Investing Often Seems Like the Safer Bet
Delaying investment can feel like a cautious financial move.
You might tell yourself:
- “The market’s too pricey right now.”
- “I’ll invest after the next downturn.”
- “The Fed could adjust rates soon.”
- “Inflation remains too high.”
- “I need to build up more cash first.”
- “I want to learn more before starting.”
These worries are perfectly natural.
The issue is that there’s always a new excuse to delay investing.
Markets may climb even when economic reports look grim, and they can drop despite strong economic indicators.
Interest rates shift. Inflation can catch investors off guard. Unexpected geopolitical events can quickly change market outlooks.
No single economic indicator can precisely predict for an individual when the market will hit its next peak or trough.
Why Spending Time in the Market Often Beats Trying to Time It
For long-term investors, a key distinction is understanding the difference between staying invested over time versus trying to time the market.
Market timing focuses on the question: “When is the best time to buy?”
In contrast, a long-term approach asks: “How long can I remain invested based on my goals and risk comfort?”
These questions are fundamentally quite different.
According to FINRA, a notable portion of market gains and losses happens within relatively brief timeframes.
The Challenge of Trying to Time the Market Bottom
Everyone hopes to buy when prices are at their lowest.
However, you can only identify the market’s lowest point after it has passed.
Picture the market dropping by 15%.
An investor hoping for a “more favorable entry” could choose to hold off, waiting for a further 10% decline.
If the market bounces back instead, that investor faces a new choice: invest now at a higher price or wait for another dip.
Understanding Dollar-Cost Averaging and Its Benefits
For those uneasy about investing at a potentially unlucky moment, dollar-cost averaging (DCA) offers a disciplined way to invest steadily instead of waiting.
According to Investor.gov, dollar-cost averaging means investing fixed amounts on a regular schedule, no matter how the market fluctuates.
When prices drop, your set investment buys more shares; when prices climb, it purchases fewer shares.
What truly matters isn’t the exact dollar amount.
When It’s Actually Wise to Hold Off on Investing
“Don’t wait” doesn’t mean you have to invest every dollar right away.
Sometimes, it’s perfectly reasonable to delay investing if other financial priorities come first.
You Lack an Emergency Savings Fund
If investing leaves you unable to cover unexpected expenses like a car repair, medical bills, job loss, or other emergencies, it’s best to hold off.
The length of your investment horizon is a critical consideration.
Funds you might need in the near future should be managed differently than money set aside for retirement decades away.
Investor.gov highlights that both your time horizon and risk tolerance play key roles in shaping the right investment strategy for you.
You Have High-Interest Debt
If you have high-interest credit card debt, investing while that debt grows can make managing your finances more complicated.
The choice isn’t just about stocks versus holding cash.
It might actually involve:
paying down debt + building emergency funds + contributing to retirement + investing, depending on your unique situation.
You’ll Need the Money in the Near Future
A portfolio aimed at a retirement goal three decades away differs greatly from funds you may need sooner.
When you can’t afford to wait for the market to bounce back, short-term fluctuations can pose a major challenge.
The longer your investment timeframe, the more opportunity you have to ride out market ups and downs, though risk remains present.
Why August Is a Good Moment to Reassess Your Investment Strategy
This period offers investors a valuable chance to check if they’re staying on track with their original investment plan.
Review Your 401(k) Contributions Before the Year Ends
For 2026, the IRS raised the employee contribution limit to $24,500 for most 401(k), 403(b), and governmental 457 plans.
The catch-up contribution limit is $8,000 for most workers aged 50 and older, while those aged 60 to 63 can contribute up to $11,250.
This makes August a convenient point to review how much you’ve contributed so far this year.
You don’t have to make any major adjustments right away.
Assess Your IRA Contribution Status
In 2026, the total contribution limit for traditional and Roth IRAs is $7,500, or $8,600 for those aged 50 and above, following the relevant regulations.
If you haven’t begun funding your IRA, the key question isn’t necessarily whether August is the ideal month to start.
A more relevant question is if delaying until a later month will genuinely benefit your long-term investment goals.
Avoid Letting News Headlines Drive Your Investment Decisions
August 2026 has already presented numerous reasons for investors to feel uneasy.
In July, the Federal Reserve held its target interest rate steady between 3.50% and 3.75%, noting that inflation remains higher than its 2% goal.
At the same time, July’s Consumer Price Index reported annual inflation at 3.4%, with energy costs rising 14.7% year-over-year and gasoline prices climbing 24.6%.
These figures are significant.
However, they don’t indicate that you should abandon your individual retirement strategy.
A smarter strategy is to distinguish economic news from your investment timeline.
How Current U.S. Economic Data Affects Investors Today
The current economic environment helps clarify why deciding “Should I invest now?” is so challenging.
- Inflation Is Still Above the Fed’s Target
- Interest Rates Are Still an Important Variable
- The Labor Market Remains Relatively Stable
What Major Personal Finance Outlets Often Overlook
Leading U.S. financial media already cover topics like market timing, dollar-cost averaging, and strategies for long-term investing in depth.
NerdWallet points out the challenges and risks involved with market timing, while placing strong emphasis on the importance of asset allocation.
Bankrate also stresses the value of maintaining consistency and regularly rebalancing portfolios instead of attempting to time the market.
Its investment coverage links market trends with Federal Reserve actions and broader economic factors.
Recently, Investopedia explored the balance between dollar-cost averaging and market timing, offering historical insights into the effectiveness of each approach.
The real editorial chance isn’t just to restate “time in the market beats timing the market.”
A better approach is to address the reader’s true concern: “What if I invest now and the market drops tomorrow?”
The response should openly recognize this risk instead of acting as if it doesn’t exist.
It’s true that markets may decline soon after you invest.
However, for investors with a long-term view, a short-term drop doesn’t automatically mean the initial choice was a mistake.
What truly counts is whether the investment aligns with the individual’s time frame, risk comfort, diversification, and financial objectives.
An Easy-to-Follow Guide for Deciding When to Invest
Rather than guessing the market’s next move, focus on answering five key questions.
1. Do I Have Funds I Can Leave Invested Long-Term?
If you’ll need the money soon, putting it into volatile investments might not be suitable.
If you’re investing for a long-term goal like retirement, you generally have more time to ride out market ups and downs.
2. Have I Built an Emergency Fund?
You shouldn’t invest money if it means you’re vulnerable to unexpected expenses.
Set aside a cash cushion that suits your situation before risking funds you might need in the short term.
3. Do I Have Costly Debt?
High-interest debt can seriously hold back your financial progress.
Before prioritizing investment gains, take a close look at the interest charges on your existing debt.
4. Is My Portfolio Diversified?
Concentrating your entire investment in a single stock, industry, or speculative asset exposes you to very different risks than spreading investments across a diversified portfolio.
Investor.gov highlights diversification and asset allocation as key strategies for managing investment risk effectively.
5. Am I Able to Stick to the Plan During Market Downturns?
This might be even more critical than perfectly timing your investment entry.
If a 15% to 20% drop would trigger panic and prompt you to sell, your portfolio may not suit your risk comfort level.
The goal isn’t to create a portfolio that never experiences losses.
Instead, the aim is to develop a financial strategy you can realistically maintain over time.
The Author’s Perspective
One of the most common errors people make is believing that investing means having to forecast the future.
That’s simply not true.
There’s no need to predict whether stock prices will climb next month.
You don’t have to foresee the Federal Reserve’s upcoming moves or pinpoint when inflation will drop back to 2%.
You need a plan that addresses three fundamental questions:
This doesn’t mean jumping into investments you don’t fully grasp.
It’s about understanding the difference between careful consideration and being stuck due to fear of uncertainty.
The most valuable investing habit might not be pinpointing the ideal day to buy.
Instead, it could be making a thoughtful choice, setting up automation when possible, diversifying, and allowing your investments time to grow.
Investor.gov highlights that consistent investing over time is a key strategy for building wealth in the long run.
Recommended Content
Savings rates are dropping
Learn how lower APYs, inflation and your savings strategy can affect your money and purchasing power.
Continue reading * You will remain on the current website