Why the annual fee on your card continues to rise
Wondering why your credit card’s annual fee keeps going up? Discover the factors behind these hikes and find out how to determine if your card remains a good deal for you.
Is Your Credit Card Becoming More Costly? Keep an Eye on the Annual Fee
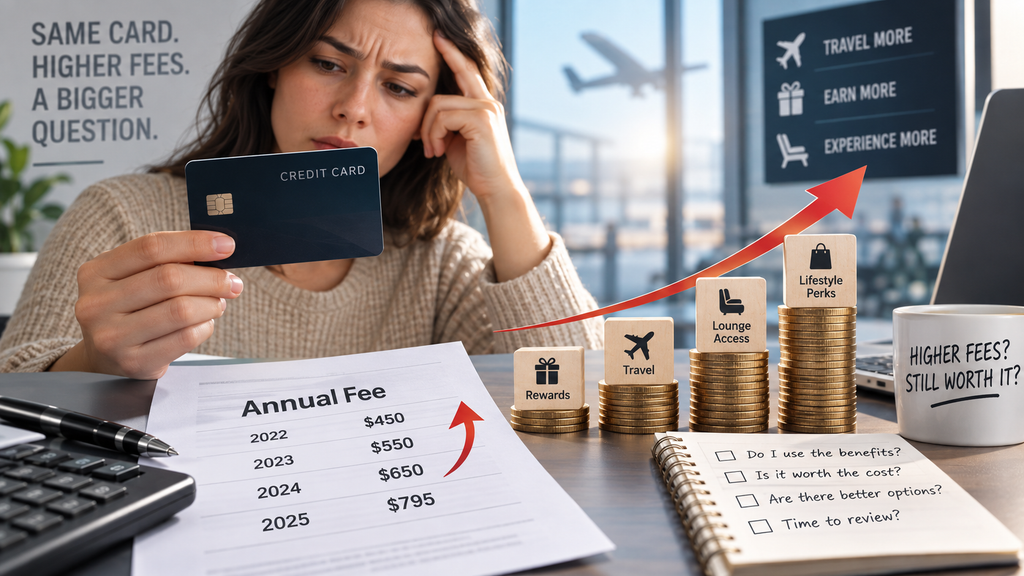
Your credit card’s annual fee might be climbing because issuers are raising prices on premium rewards, adding perks like travel and lifestyle benefits, tweaking card economics, and targeting customers who spend more.
An increased fee doesn’t necessarily mean the card is a better or worse value.
The main consideration is whether the perks you actually use outweigh the higher annual charge.
What Causes Credit Card Annual Fees to Rise?
An annual fee on a credit card may rise when the issuer updates the card’s pricing structure or its benefits.
High-end cards have increasingly added perks like travel credits, lounge access, rewards, and lifestyle benefits, often alongside fee hikes.
For instance, changes to some premium cards have driven annual fees close to or exceeding $800 annually.
The key difference lies between the issuer’s advertised value and the actual worth you get from the card.
What Causes Credit Card Annual Fees to Go Up?
Common reasons for these increases include:
- New travel credits
- Expanded airport lounge access
- Higher rewards rates
- Additional hotel or dining perks
- Extra statement credits
- Updates to the rewards program
- Rising costs of premium rewards
- Targeting higher-spending customers
Are Annual Fees on Credit Cards Increasing Across the Industry?
Fee hikes have been especially notable among premium credit cards.
The Federal Reserve Bank of New York noted that U.S. credit card debt reached $1.26 trillion in Q2 2026, underscoring the ongoing role of credit cards in household budgets.
Among premium cards, annual fees have climbed to several hundred dollars, with some cards charging close to or even above $800 per year.
What’s Driving Premium Credit Cards to Increase Their Annual Fees?
These premium cards often try to stand out by bundling together a variety of travel and lifestyle perks.
A higher annual fee usually signals a pricier benefits package, but having more perks doesn’t always translate to greater value for each cardholder.
Travel Credits Can Help Offset a Steep Annual Fee
Imagine a card with a $795 annual fee that offers $300 in travel credits.
The straightforward math looks like this: $795 − $300 = $495
However, the $300 credit only holds its full value if you would have spent that amount on qualifying purchases anyway.
If you redeem just $150 of that credit, then the real value to you is closer to $150, not the full $300.
This distinction is crucial when assessing the true worth of premium credit cards.
The Value of Airport Lounge Access Varies Among Travelers
Access to airport lounges can be especially worthwhile for those who travel often.
For travelers who fly multiple times yearly, lounge access might replace expenses they’d otherwise incur at the airport.
But for those who seldom travel by air, this perk may offer little real benefit.
Don’t judge a perk by its listed cost. Instead, consider how much money it actually helps you save.
Rewards Only Have Value When They Align With Your Spending Habits
A higher rewards rate can help balance out an annual fee if it applies to purchases you already make regularly.
However, spending extra just to earn rewards can undermine the whole point.
For instance, if a card gives bonus points on dining, it doesn’t mean that charging an unnecessary $500 restaurant meal actually saves you money.
Rewards should reflect your existing spending, not drive you to spend more.
Is It Worth Keeping Your Credit Card After the Annual Fee Goes Up?
Before deciding to keep, switch, or cancel the card, consider several important factors carefully.
Compare It Against Cards With No Annual Fee
Avoid limiting comparisons to only other premium credit cards.
Evaluate its net yearly value against a card that carries no annual fee.
Check with Your Issuer About Switching Products
Before you decide to close your card, see if the issuer offers an option to switch to a different card product.
Based on the issuer and your account, you might be eligible to downgrade to a card with a lower or no annual fee.
This option isn’t available with all issuers.
Is It Legal for Credit Card Companies to Increase Your Annual Fee?
In general, federal regulations allow certain annual or monthly maintenance fees to rise after the first year, as long as the required rules are met.
Regulation Z along with CFPB guidelines set forth notification rules for specific changes to credit card terms.
Certain modifications require a 45-day advance notice, though the exact timing depends on the nature of the change.
What Amount of Notice Must a Credit Card Issuer Provide?
For changes governed by Regulation Z, cardholders typically get advance notification before the change takes effect.
The notice should outline key details such as:
- The updated fee amount
- The date the change starts
- Which account terms are affected
- Any rights or choices you have
Be sure to carefully review the issuer’s notice, as requirements vary by fee and account type.
Is It Possible to Avoid Paying a Credit Card Annual Fee?
Sometimes you can. Your choices might include:
- Switching to a no-fee card from the same issuer;
- Inquiring about possible product changes;
- Comparing this card with other options you have;
- Contacting your issuer to see if retention offers exist;
- Closing the card after weighing impacts on your credit.
Will Closing a Credit Card Impact Your Credit Score?
Shutting down a credit card can influence the elements that affect your credit score.
A key factor to keep in mind is credit utilization.
How Should You Manage a Credit Card Balance?
If you carry a balance month after month, the annual fee isn’t the only factor to worry about.
The Federal Reserve Bank of New York noted that U.S. credit card balances reached $1.26 trillion in the second quarter of 2026.
For cardholders with revolving debt, the cost of interest often outweighs any benefits gained from reward optimization.
Should You Spend More to Offset an Annual Fee?
Any financial analysis should avoid assuming extra spending you wouldn’t normally do.
When a card has a $500 yearly fee, spending thousands more just to earn rewards can end up costing you extra instead of saving money.
The aim shouldn’t be to rack up enough rewards to make spending more worthwhile.
Instead, focus on getting the most value from purchases you intended to make anyway.
Author’s Opinion
A rising credit card annual fee warrants a fresh review, especially when the increase reaches several hundred dollars.
What matters isn’t simply that the issuer has added more perks. What counts is if those perks align with how you actually spend, travel, and use your card.
When you already take advantage of the credits and rewards, the increased fee might be balanced out by benefits you would have bought regardless.
If you don’t redeem those perks, the stated value can be deceptive for your own budget.
The easiest way to evaluate is to ask: how much did I actually save in the past year, and what was my total cost for the card?
That calculation provides a far clearer understanding than relying on the promotional value attached to every feature.
Also, if you carry a balance, prioritize understanding your interest charges before focusing on maximizing rewards.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website