Credit card debt wearing you down? Here’s why personal loans are becoming the go-to solution
Carrying credit card debt at over 22% APR is taking a toll on your finances. Discover how personal loans can help reduce your expenses, what interest rates look like following the recent Fed increase, and the best time to make the switch.
Beware: minimum payments keep you trapped in debt
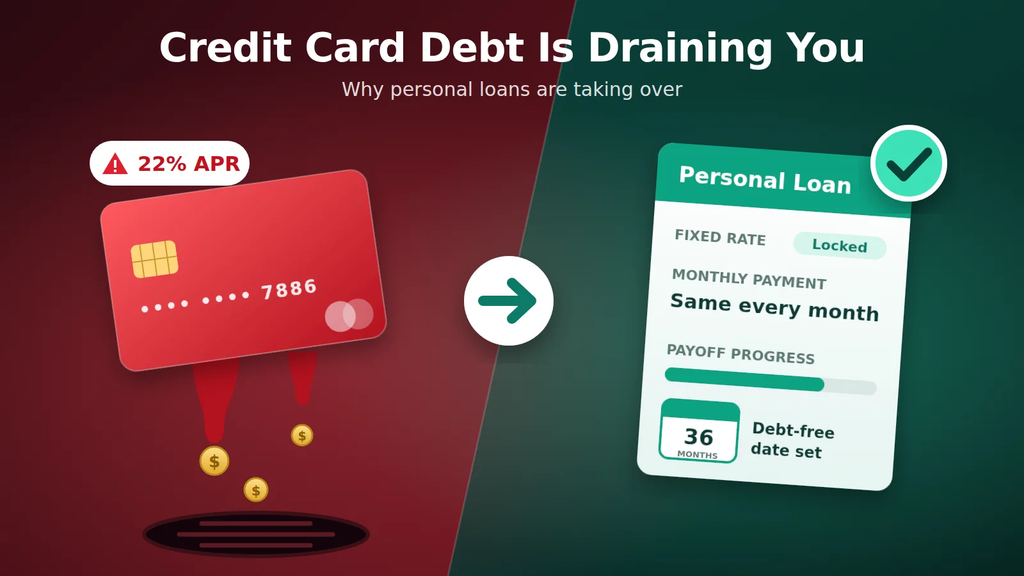
Credit card debt is wearing you down, and it’s more than just a feeling.
If your September credit card statement included back-to-school expenses on top of a balance that never seems to shrink, you’re far from alone.
Currently, Americans carry $1.263 trillion in credit card debt, according to the Federal Reserve Bank of New York.
As a result, millions are quietly shifting their credit card debt into personal loans.
These loans offer fixed interest rates, set monthly payments, and a clear payoff date. We’ll explain why this shift is happening, what the numbers reveal, and how to determine if it’s the right move for you.
H2: Why Credit Card Debt Is Draining Your Finances Today
According to the latest Federal Reserve figures, the typical APR on credit card accounts carrying a balance is 22.15%. Interest rates vary based on credit quality. WalletHub reports that new credit card rates average 27.01% for fair credit and 23.27% for those with good credit.
With an APR of 22.15%, carrying an average balance of $7,886 means you’re paying roughly $146 a month just in interest. This is money that doesn’t reduce your principal balance at all.
The Fed’s September rate increase makes things tougher
The FOMC unanimously voted 12–0 to increase the federal funds rate to a range of 3.75%–4.00%.
Fed Chair Kevin Warsh stated that “inflation remains too high and has persisted for far too long.” Inflation currently stands at 3.4%, with 16 out of 18 officials anticipating at least one more rate hike before the year ends.
Since most credit cards have variable APRs linked to the prime rate, these increases affect you directly.
Ted Rossman, former lead analyst at Bankrate, notes that Fed rate adjustments usually “pass through to consumers within one or two months” and impact both new charges and existing balances.
Back-to-school expenses just arrived
Spending from August is now appearing on September credit card bills. According to a NerdWallet survey, 19% of parents anticipated going into credit card debt due to back-to-school expenses, while 24% intended to use Buy Now, Pay Later options.
An Increasing Number of People Are Falling Behind
The New York Federal Reserve reports that the portion of credit card balances in serious delinquency (90+ days past due) rose to 6.97% in the second quarter of 2026.
Joelle Scally, Economic Policy Advisor at the New York Fed, cautioned that “new delinquencies on auto loans and credit cards continue to stay at high levels.”
How Much Can You Save by Making the Switch?
Can consolidating your debt improve your credit score?
Yes, it often does. According to a TransUnion study, 68% of people who consolidated their debts experienced a credit score increase of more than 20 points.
On average, card balances decreased from $14,015 to $5,855. “Debt consolidation loans generally achieve their intended results,” said Liz Pagel, formerly SVP at TransUnion.
H2: Is Taking Out a Personal Loan the Right Choice for You?
When a personal loan could be a smart move
- Your new loan’s APR is noticeably lower than your credit card APR, including fees;
- You can comfortably handle the fixed monthly payments;
- You’re determined to avoid racking up your cards again after payoff;
- Your credit score is 690 or above, placing you in better rate brackets.
Beware of These Potential Pitfalls
- Origination fees: some lenders subtract these from your loan, so focus on the APR rather than just the interest rate;
- Fair or poor credit: average rates between 23.73% and 27.27% might not be better than your card’s rate;
- Increasing delinquencies: personal loan late payments (60+ days) rose to 3.81%. Only borrow what you can repay;
- Don’t rely on a rate cap: the suggested 10% credit card interest cap isn’t law. Waiting for it might cost you months of extra interest.
How to Move From Credit Card Debt to a Personal Loan in 5 Simple Steps
Step 1: Write Down Every Card Balance and APR
Before reaching out to lenders, make sure you know exactly how much you owe and what those debts cost you. Grab the latest statement for each card and note down:
Find the “Interest Charge” section on each statement. This amount is what you pay monthly without lowering your actual balance by even a penny.
The typical balance is $7,886 with an average APR of 22.15%. With those figures, your monthly interest charges add up to roughly $146 each month.
Step 2: Check Your Credit Score for Free
Your credit score plays the biggest role in determining your loan rate. The gap between score levels can be significant:
Data source: NerdWallet, September 2026.
Most banks and credit card companies let you check your credit score at no cost.
For complete credit reports, visit AnnualCreditReport.com, the authorized site offering free weekly credit reports from Equifax, Experian, and TransUnion.
Step 3: Get Prequalified by At Least Three Lenders
Prequalifying lets you see your estimated rate, loan amount, and monthly payments without affecting your credit score, since lenders perform only a soft credit check.
A hard credit check occurs only once you submit a formal loan application.
Be sure to compare at least one lender from each category:
- Online lenders: quick approvals, often funding within days, with simple online prequalification;
- Banks: may provide lower rates if you’re an existing customer. The Fed reports an average of 11.86% on 24-month bank personal loans;
- Credit unions: federal credit unions usually cap rates at an 18% APR limit, making them a good choice if your credit isn’t flawless.
Pro tip: try to find lenders offering “direct payments to creditors.” This means the loan funds go straight to your credit card companies, so the money never touches your bank account.
Step 4: Evaluate APR, Fees, and Overall Cost
The advertised rate rarely tells the whole story. Make sure to review these details when comparing offers:
- APR, not just interest rate: APR includes origination fees, revealing the true annual cost;
- Origination fee: some lenders deduct this fee upfront. For example: a 5% fee means you’d need to borrow about $8,301 to get the full $7,886 to pay off your cards;
- Loan term: longer terms reduce monthly payments but increase total interest paid;
- Prepayment penalty: confirm you can pay off the loan early without extra fees.
Here’s how different terms affect the cost of a $7,886 loan at a 19.55% APR:
H3: Step 5: Immediately Settle Your Credit Cards and Activate Autopay
After your loan is approved and the funds arrive, take action the very same day:
- Pay every card balance in full. If your lender offered direct pay, confirm the payments went through;
- Check each card account a few days later to confirm a $0 balance. Interest charged in the last cycle can leave a small leftover amount;
- Set up autopay on the new loan so you never miss a payment. Some lenders also give a small rate discount for autopay;
- Keep your card accounts open. Closing them can hurt your score by increasing your credit utilization and shortening your credit history.
Paying off your cards lowers your credit utilization rate, which is one of the quickest ways to boost your credit score.
A TransUnion report showed that 68% of borrowers who consolidated their debt saw credit score increases exceeding 20 points.
Step 6: Safeguard Your Progress to Prevent Debt from Returning
This is the point where many stumble. Using a loan to clear your cards only works if you keep those card balances at zero afterward.
If not, you risk ending up with twice the amount of debt.
- Take your cards out of your wallet and remove saved cards from online stores and apps;
- Plan ahead for the holidays. Holiday shopping is weeks away, so set a cash budget now, before the season starts;
- Build a small emergency fund, even $500 to $1,000. Most people rack up card debt again because of an unexpected expense, like a car repair or a medical bill;
- Turn on spending alerts in your card apps so any new charge shows up right away;
- Use your cards for one small bill only, such as a streaming service on autopay. That keeps the account active without letting a balance build up.
Author’s Opinion
Having reported on personal finance for over ten years, I can confidently say this moment feels unique.
Card balances are at record levels, APRs exceed 22%, and the Fed has raised rates instead of lowering them.
Families carrying balances face pressure from all directions. I’ve seen too many hold out for rate cuts or government limits, while quietly losing hundreds each month to interest.
A personal loan isn’t a cure-all and won’t suit everyone. If your credit is only fair or poor, the numbers might not add up, and speaking with a counselor could be a wiser first step.
However, if you can secure a significantly lower fixed rate, locking it in before another hike is one of the smartest financial moves you can make this season.
Recommended Content
Your flood coverage might expire this month
Find out what happens after your coverage lapses, how NFIP renewal works, and what you should verify beforehand.
Continue reading * You will remain on the current website