Credit score and credit report: essential insights before you apply
The phrases credit score vs credit report are frequently confused, but they actually represent two distinct concepts.
If you’re planning on applying for a credit card, you’ve probably heard people say “Check your credit!” But what does that really mean? Understanding this now can help you make smarter choices when it’s time to apply for credit.
Understanding the difference between your credit score and credit report
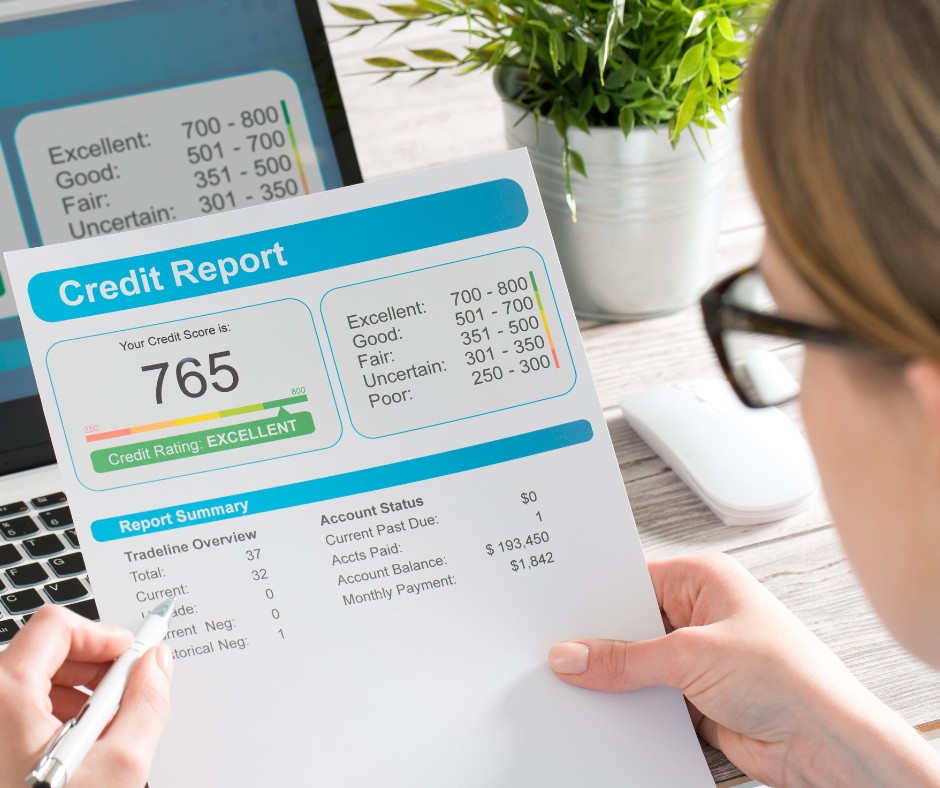
Your credit report is a comprehensive summary of your credit activities. It lists your open accounts, outstanding balances, payment history, and hard inquiries from lenders who have reviewed your credit. Think of it like a transcript from school—it records the entire history, not just the final grade.
Meanwhile, your credit score is a numeric value, typically between 300 and 850, calculated from the data in your credit report. It serves as a quick snapshot of your credit reliability. Lenders rely on this score to rapidly judge the likelihood of you repaying borrowed money.
Simply put, the credit report tells the whole story, while the credit score offers a quick summary.
Why this distinction matters when you apply for a credit card
When applying for a credit card, it’s crucial to know how these two elements differ and what each reveals about your credit.
Many people get frustrated after being turned down for a credit card despite believing they had good credit. Often, the real problem is a hidden detail in the credit report—like a late payment or a high balance—that lowers their credit score without them realizing it.
Credit card
How do credit cards work?
See our beginner’s guide to fees, APR, and rewards.
LEARN MORE * You will remain on the current websiteCredit card issuers review both your credit score and report when deciding on applications. The score offers a quick snapshot, but they examine the report for deeper details.
For instance, two individuals might share the same credit score yet have very different credit histories. One could have a strong track record with low debt, while the other might show recent missed payments. Such differences can heavily influence approval decisions.
How to view and track both your credit score and report
You have the right to receive one free credit report annually from each of the three main credit reporting agencies: Equifax, Experian, and TransUnion. Websites like AnnualCreditReport.com make it simple to obtain these reports.
Your credit score isn’t always included with those free reports. However, many banks, credit card providers, and financial apps offer complimentary access to your score. Just be sure to confirm which scoring model you’re viewing (FICO or VantageScore), since lenders may rely on different versions.
Keeping a regular eye on your credit helps you spot mistakes, measure your progress, and avoid unexpected issues when applying for credit.
Credit card
Credit card benefits you’re probably not using
…but should!
LEARN MORE * You will remain on the current websiteKey steps to take before applying
Before you fill out any credit card application:
- Check your credit report for any mistakes.
- Be aware of your current credit score.
- Reduce high balances if you can.
- Avoid multiple applications in a short period to prevent score drops from hard inquiries.
Understanding your complete credit profile lets you apply with more confidence and reduce the chances of being turned down.
Credit Score vs credit report: how this key difference can save you time and hassle
Grasping the distinction between a credit score and credit report might seem minor, but it’s crucial for managing your finances. It helps you identify warning signs, take effective steps, and avoid the confusion of not understanding why your card application was declined.
Before hitting “apply,” spend a moment reviewing both—your future self will be grateful you did.