Loan Rates: Don’t Miss the Crucial September 30 Deadline
Discover how making automatic payments by the September 30 deadline can help reduce interest rates on qualifying federal student loans.
Is Your Loan Interest Rate Too High? Actions to Take Before September 30
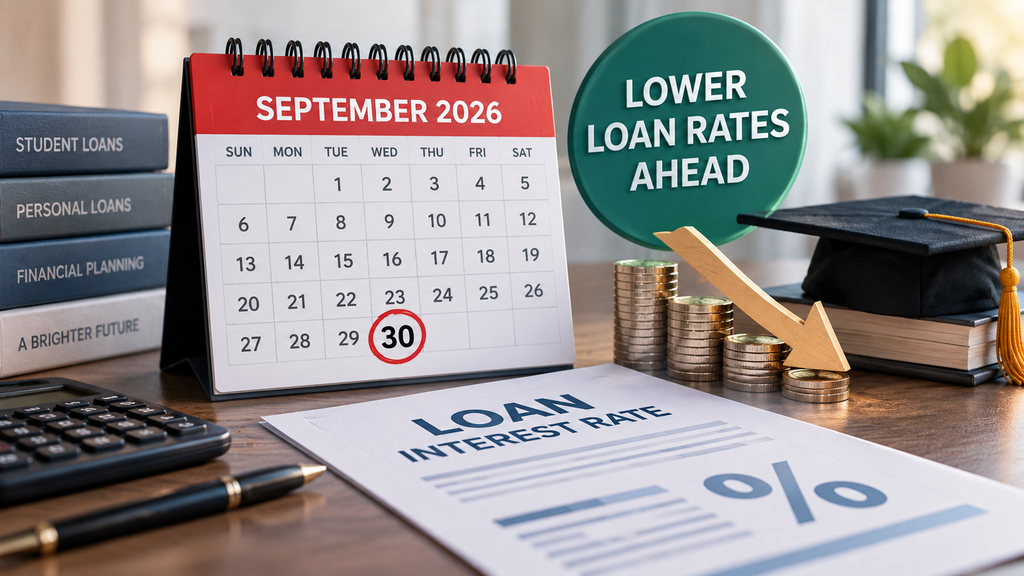
September 30, 2026, marks a key deadline for federal student loan borrowers who qualify for special benefits.
By signing up for automatic payments before 11:59 p.m. on that day, you could receive a temporary 1% interest rate cut on your loan until June 30, 2028, according to the U.S. Department of Education.
This cutoff date does not affect all loan types. It specifically applies to qualifying federal student loans and the Auto Pay interest rate discount.
If you want to reduce your borrowing expenses, here’s what the September 30 deadline involves, who’s eligible, how the rate reduction works, and what to verify before the deadline.
Understanding the September 30 Loan Interest Rate Deadline
The September 30 cutoff marks the final day for eligible federal student loan borrowers to sign up for Auto Pay and secure a temporary 1% reduction in their interest rate.
Starting July 1, 2026, the U.S. Department of Education boosted the Auto Pay interest discount from 0.25% to a full 1 percentage point.
Borrowers who enroll by September 30 will enjoy this reduced rate until June 30, 2028.
Why Is the September 30 Deadline Important?
Reducing your loan interest rate can lower the amount of interest that builds up on your outstanding student loan balance.
How much you save depends on factors like your loan balance, repayment plan, and how much time remains on your loan.
For instance, if you owe $30,000, lowering your interest rate from 7% to 6% could save roughly $300 in interest annually, before considering any principal payments.
This example is for illustration only and does not guarantee actual savings for any borrower.
Does the September 30 Deadline Apply to Every Loan?
No. This is a crucial distinction to keep in mind.
The September 30 deadline does not require refinancing personal loans, mortgages, auto loans, or private student loans by that date.
This temporary 1% reduction applies only to eligible federal student loans with Auto Pay enrollment.
Who Qualifies for the 1% Interest Rate Discount on Loans?
Federal student loan borrowers who sign up for Auto Pay by September 30, 2026, are eligible for the temporary 1 percentage point interest rate cut.
The Department of Education states that the enhanced interest rate reduction applies only to eligible Direct Loans disbursed on or after July 1, 2012.
You should verify your individual eligibility by checking with your loan servicer.
What If You Already Have Auto Pay?
If you’re currently signed up for Auto Pay, you typically won’t need to register again.
The updated plan raises the total Auto Pay discount to 1 percentage point, so borrowers who had a 0.25% discount before can now get an extra 0.75 percentage-point cut.
Log in to your servicer account to verify how the discount is applied to your loans.
The Importance of Loan Interest Rates for Borrowers in 2026
Borrowing expenses continue to be a key concern for households across the U.S.
On September 16, 2026, the Federal Reserve increased the federal funds target range by 0.25 percentage points to 3.75%–4%.
In a separate update, the Federal Reserve Bank of New York announced that total U.S. household debt hit $18.8 trillion in the second quarter of 2026.
These numbers don’t set the exact interest rate an individual borrower receives. Each loan type follows its own pricing rules.
Still, they help explain why borrowers keep a close eye on borrowing rates.
How Does the Federal Funds Rate Affect My Loan?
The federal funds rate isn’t the interest rate applied to your personal or student loans.
Rather, it’s the rate banks charge each other for lending reserve balances overnight.
Monetary policy shifts can affect the overall financial landscape, but how much an individual loan changes depends on its credit type and the way its interest rate is set.
This difference is key to keep in mind when you see news about loan rates “dropping” or “increasing.”
Loan Interest Rate vs. APR: How Do They Differ?
The interest rate indicates the percentage charged on the money you borrow, whereas the APR offers a more comprehensive view of the yearly cost, including some fees.
When comparing personal loans, APR is especially helpful because loans with the same interest rate might have varying fees that affect the true cost.
Why This Is Important When Comparing Personal Loan Offers
NerdWallet found that personal loan APRs typically vary between about 6% and 36%, influenced by both the lender and the borrower’s profile.
The September 2026 report also highlighted wide variations in average prequalified APRs depending on an individual’s credit standing.
This shows that the APR someone else gets isn’t necessarily what you will be offered.
How to Find Your Loan Interest Rate Before the September 30 Deadline
The quickest way to find out if this deadline affects you is by checking your federal student loan account and your Auto Pay enrollment.
Here’s what to do:
Step 1: Verify Your Current Loan Interest Rate
Sign into your federal student loan servicer’s website.
Note down the interest rate for each of your loans.
Step 2: Confirm Your Auto Pay Status
Navigate to the payment settings and check if Auto Pay is currently enabled on your account.
If you haven’t signed up yet, follow the enrollment steps outlined by your loan servicer.
Step 3: Confirm Your Interest Rate Discount
Check for details indicating if the Auto Pay interest rate discount is applied to your loan.
If you can’t locate this detail, reach out to your loan servicer for assistance.
Step 4: Verify Your Bank Account
Ensure the bank account linked to Auto Pay is active and has enough funds to cover the scheduled payments.
Step 5: Keep Your Enrollment Confirmation
Once you’ve enrolled, be sure to save your confirmation email or any proof of enrollment.
Keeping this confirmation can be helpful if you need to address any issues with your account later on.
Is the September 30 Deadline Relevant for Personal Loans?
No. Borrowers with personal loans are not automatically eligible for the 1 percentage-point interest rate cut by September 30.
If your personal loan carries a high interest rate, there may be alternative strategies to lower your borrowing expenses.
These options might include:
- Evaluating different refinancing offers
- Consulting your current lender about lower rates
- Improving your credit score before applying
- Comparing loan options by their APR
- Shortening the loan term if you can afford it
Keep in mind that refinancing should be assessed based on the overall expense of the new loan, not only on the stated interest rate.
What Are the Consequences of Missing the September 30 Deadline?
Failing to meet this deadline doesn’t mean you won’t be able to reduce your borrowing costs in the future.
Still, you might lose the chance to take advantage of the temporary boosted Auto Pay discount available only during the September 30 enrollment period.
Here’s what happens if you miss the deadline:
- Review your federal student loan account.
- Reach out to your loan servicer about possible benefits.
- Explore your repayment plan options.
- Assess other debts with high interest rates.
- For personal loans, separately evaluate refinancing choices.
It’s important to separate this federal student loan benefit from other options like refinancing or negotiating different types of debt.
Borrowers’ Financial Checklist for September 2026
September is a great time to take stock of your borrowing expenses.
During September, the Bureau of Labor Statistics is set to release key economic data, including the August jobs report on September 4, the Consumer Price Index for August on September 11, and JOLTS figures on September 29.
While these reports don’t directly set your personal loan interest rate, they offer valuable insight into the overall economic landscape.
Review Your Debts
Make a straightforward list that includes:
- Loan balance
- Loan interest rate
- APR
- Monthly payment
- Remaining term
- Potential fees
Spot Where Your Costs Might Be Highest
Start by focusing on debts that carry the steepest interest rates.
Credit cards and certain personal loans often have much higher interest rates compared to other consumer credit types.
Look Into Available Discounts
Check if your lender or loan servicer provides perks or discounts related to:
- Enrollment in Auto Pay;
- Established relationships with lenders;
- Participation in certain repayment plans;
- Other qualifying factors.
Be sure to confirm all terms directly with your loan provider.
Writer’s Perspective
Understanding the September 30 deadline is crucial because it marks a defined chance for qualified federal student loan holders—not a universal deadline for all loans nationwide.
Borrowers who are eligible should review their Auto Pay status before the deadline to confirm they’re receiving the applicable interest rate discount.
For everyone else, the takeaway is clearer: avoid making borrowing choices based only on a headline about loan rates.
When weighing debt options, consider the loan’s interest rate, APR, fees, monthly payments, repayment length, and overall cost together.
This approach provides a more accurate view of what the loan truly costs and whether refinancing or switching makes sense for your finances.
Recommended Content
Why your card’s annual fee keeps climbing
Learn what drives increases and how to calculate whether your card is still worth it.
Continue reading * You will remain on the current website