Credit Card Market: Grasping the Two-Tier Division
Discover how the credit card landscape is dividing based on credit quality, and what factors like APRs, rewards, credit scores, and debt reveal about American consumers.
What’s driving the split into two tiers in the card market?
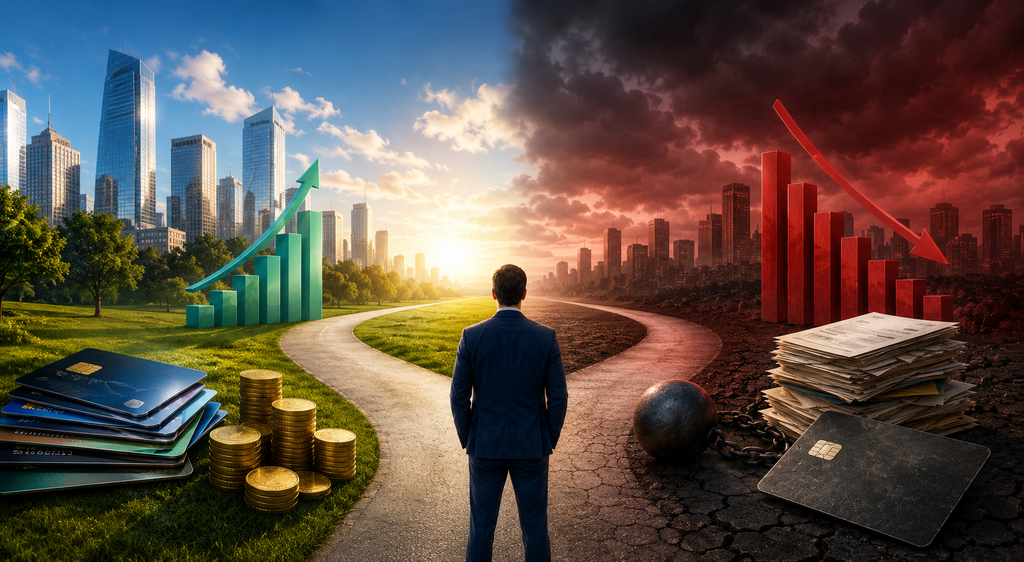
The credit card market is becoming more segmented based on credit quality.
Those with strong credit scores often qualify for lower-cost deals, higher credit limits, 0% introductory APRs, and premium rewards cards.
This doesn’t imply the U.S. credit card sector officially recognizes a “two-tier” system. Rather, it reflects a widening gap in how consumers experience the market depending on their credit standing.
Meanwhile, Bankrate noted the average credit card interest rate was 19.56% as of late August 2026.
Understanding the Two-Tier Structure of the Credit Card Market
The two-tier credit card market refers to the distinction between consumers with strong credit scores and those considered higher-risk borrowers.
To put it simply:
The Consumer Financial Protection Bureau (CFPB) categorizes credit risk into groups such as super-prime, prime, near-prime, subprime, and deep-subprime borrowers.
The framework classifies consumers with FICO Score 8 ratings of 720 and above as super-prime, while those scoring under 580 fall into the deep subprime category.
The Importance of Credit Scores in the Credit Card Industry
Your credit score gives lenders an estimate of how likely you are to repay money you borrow.
A higher credit score often qualifies you for credit cards with better, more competitive offers.
Conversely, a lower credit score can increase borrowing costs, as lenders see these accounts as higher risk.
Put simply, your credit quality affects not just your eligibility for a card, but also the cost you’ll pay for that credit.
What’s Driving the Growing Segmentation in the Credit Card Market?
The credit card market is becoming increasingly divided as lenders adjust pricing and credit management based on risk levels.
There are three key factors to consider:
- Credit risk;
- Interest rates;
- Consumer demand for rewards and credit.
How Credit Risk Influences Borrowing Costs
Credit cards represent unsecured loans, meaning the lender cannot claim assets like a home or car if the borrower fails to repay.
Because of this, a borrower’s credit history is crucial in setting the loan conditions they receive.
The CFPB notes that credit card APR margins have climbed over the last ten years, despite the proportion of cardholders with subprime scores staying fairly consistent.
This helps clarify why two individuals applying for credit cards simultaneously might receive very different offers.
How Interest Rates Increase the Cost of the Credit Divide
Carrying a balance on a credit card continues to be costly.
According to Bankrate, the average credit card interest rate was 19.56% in late August 2026. Although this is lower than the record high of 20.79% seen in August 2024, it still makes carrying debt quite expensive.
If you pay off your statement balance in full every month, the APR may have minimal effect on your finances.
But for those who carry a balance, the APR often becomes one of the most critical figures to watch on their account.
How the Two Market Segments Influence Credit Card Rewards
The split impacts more than just the interest rates charged.
It also influences eligibility for rewards programs, special promotions, and premium card perks.
Consumers with Strong Credit Typically Have More Reward Choices
Those with higher credit scores often qualify for cards that provide:
- Cash back rewards
- Travel perks
- Sign-up bonuses
- Introductory 0% APR deals
- Access to airport lounges
- Travel statement credits
- Purchase protection benefits
For instance, NerdWallet’s credit card marketplace separates options into categories like 0% APR cards and rewards cards, highlighting how fiercely these types of cards compete for users.
However, rewards shouldn’t always be seen as actual savings.
A card offering 2% cash back can earn you $20 in rewards from $1,000 in qualifying purchases.
But if those purchases add to a balance that accrues interest, the cost of carrying that debt often exceeds any reward earned.
Consumers with Lower Credit Scores Often Gain Less from Rewards Programs
The CFPB has identified notable disparities in rewards offered across different credit-risk categories.
According to its 2023 consumer credit card report, subprime cardholders earned less than one percentage point in annual rewards relative to their balances, whereas super-prime cardholders with larger spending volumes could lower their effective credit costs by nearly five percentage points thanks to rewards.
This highlights a key feature of the two-tier credit card market:
Those who stand to gain the most from rewards are usually the ones able to steer clear of interest charges by paying their balances off in full each month.
How the Two-Tier Credit Card Market Impacts You
The real effects depend mostly on whether you carry a balance and where your credit score stands.
If Your Credit Is Strong
With a solid credit history and a habit of paying your balance in full, you’ll likely have more options to choose from, including:
- Lower-cost credit
- 0% introductory APR offers
- Cash-back cards
- Travel rewards
- Premium benefits
- Higher credit limits
Qualifying for a premium card doesn’t always mean it’s the best option for you.
Make sure to compare the annual fees, APR, and the true benefits of the rewards offered.
If Your Credit Is Fair or Poor
When your credit score is lower, your goals might need to shift accordingly.
Instead of focusing mainly on rewards, consider these factors:
- APR
- Annual fees
- Security deposit requirements
- Credit limit
- Reporting to the major credit bureaus
- Late-payment policies
- Opportunities to build a positive payment history
Data from the CFPB reveals that consumers with credit scores below prime often encounter much higher APR spreads, making borrowing costs a critical factor.
A credit card focused on rebuilding credit affordably can be more beneficial than one offering flashy rewards.
How to Get the Most From the Credit Card Market
Having a perfect credit score isn’t necessary to make smarter choices with credit cards.
Your aim should be to select a card that aligns with your current financial needs.
Review Your Credit Before Applying
Begin by checking your credit score along with your credit reports.
The CFPB’s credit risk model helps lenders identify varying degrees of creditworthiness.
Understanding your credit status can prevent you from applying to cards that don’t suit your financial profile.
Prioritize Comparing APR Over Rewards
If you tend to carry a balance, your top priority should generally be the APR.
For instance, a card offering a slightly lower rewards rate but a much lower APR might be a better choice for those who often carry debt.
Data from Bankrate shows the average credit card APR is close to 20%, highlighting the high cost of revolving balances.
Avoid Letting Rewards Drive Overspending
Rewards are created to motivate you to use your card more often.
That doesn’t mean rewards are bad. However, they shouldn’t be an excuse to spend beyond what you can repay.
A good rule of thumb: if you can’t comfortably clear your balance, prioritize calculating interest costs over chasing rewards.
Key Credit Card Market Trends to Watch in 2026
The credit card industry will likely stay closely linked to consumer credit health, interest rate changes, and household debt levels.
Lenders Are Focusing More on Credit Risk Factors
According to TransUnion, U.S. consumer credit is increasingly diverging in a K-shaped pattern, with lenders adjusting their approach based on different credit risk levels.
For instance, new credit card lines for super-prime consumers grew by 11.5% to $12,511, while new credit lines for deep-subprime consumers increased by 5.5% to $678.
That gap is quite substantial.
This indicates that credit availability isn’t simply growing or shrinking uniformly across all segments of the market.
Credit is becoming more accessible at varying rates for different groups of consumers.
Why Interest Rates Will Remain Important
Credit card interest rates tend to track overall trends in general interest rates.
Since many credit cards have variable APRs, shifts in benchmark rates usually lead to changes in borrowing expenses.
For those who carry a balance, even modest APR adjustments can have a significant impact over time.
Rewards Will Stay Competitive, but They Aren’t Free Money
Issuers continue to use rewards as a key tool to attract new cardholders.
However, the true worth of rewards depends largely on how people manage their card spending.
The CFPB has closely studied how rewards relate to card usage and credit costs, uncovering notable variations among different credit-risk categories.
As a result, consumers should consider rewards within the full cost-benefit context of a card, not simply as an isolated perk.
The Author’s Perspective
One of the biggest errors consumers make when examining the credit card market is assuming everyone faces the same conditions.
That’s not the case. Someone with an excellent credit score who pays off their balance in full each month can use credit cards to earn cashback, accumulate travel points, or benefit from special financing offers.
Meanwhile, a person carrying a balance with a high APR will experience that same market in a very different way.
For this reason, I think the best way to grasp the “two-tier” credit card market isn’t just by looking at which cards exist.
Instead, ask yourself: What is the true cost of credit for me?
If your credit score unlocks better options, make sure to use this advantage wisely.
If your credit stands on shaky ground, prioritize strengthening your finances instead of pursuing rewards that might not benefit you.
Recommended Content
Student loan collection
Learn who is at risk, what collections can take and how to protect your finances.
Continue reading * You will remain on the current website